 Payment Institution
Obtained Nexpay’s FCA Authorised Payment Institution licence.
WhatsApp and Telegram +44 7563 115980
[email protected]
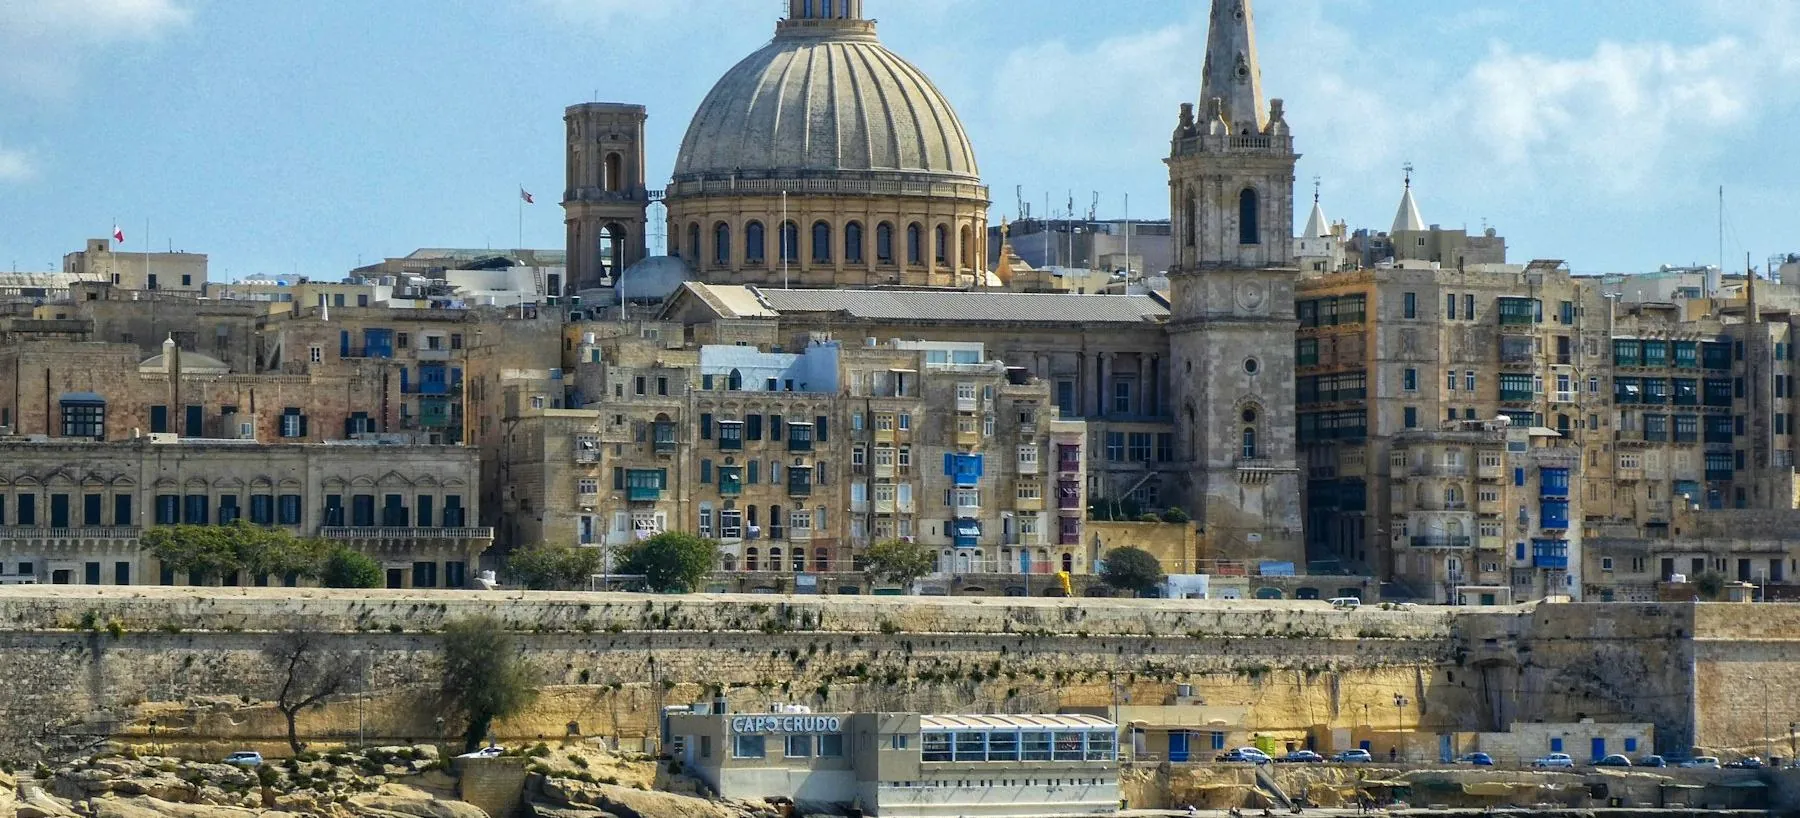
Payment firms working with gaming operators and other EU merchants choose Malta for a rulebook that sets out governance in detail and a regulator that publishes its service targets.
Selected engagements from more than 250 licences obtained since 2013, for payment, e-money and cryptoasset firms.
 Volkswagen
 Payment Institution
Obtained Nexpay’s FCA Authorised Payment Institution licence.
 Electronic Money Institution
Obtained Dzing Finance’s FCA Authorised Electronic Money Institution licence.
Obtained Orbital’s FCA Authorised Payment Institution licence.
Our realistic timeline from submission to decision.
Safeguarding, operating and settlement accounts opened alongside the application, so you trade on authorisation.
We assemble your team: two directors in Malta, a compliance officer and MLRO.
The licence, the requirements, the cost and the timing for your business.
You will need two directors running the business from Malta, a board of three with an independent chair and a Malta-resident member, a compliance officer and an MLRO.
One programme, from scoping to launch. Speak to an expert about this licence.
Requirements, capital, timing, fees and common questions, drawn from the regulator’s own publications.
A business providing a payment service in Malta or, through passporting, in the EU and EEA needs an MFSA licence. A business that will also hold customer balances applies for an EMI licence instead.
| Requirement | Amount |
|---|---|
| Account, card and other services (a–e) | €125,000 |
| Money remittance only | €20,000 |
| Payment initiation only | €50,000 |
| Account information only | Registration; no initial capital stated |
| Ongoing own funds | Method A, B or C as determined |
Own funds may never fall below the initial capital.
| Figure | Value | Source |
|---|---|---|
| Statutory decision period | 3 months from receipt; silence is a deemed refusal | Financial Institutions Act, Cap. 376 |
| Regulator’s published figure | Replies to applicant feedback within 20 working days, about 1 month, at each stage | MFSA authorisation process service charter |
| Application preparation | 6 to 8 weeks | From instruction to submission, including banking in parallel |
| Our realistic timeline | 6 to 8 months after submission | Our own figure, from the regulator’s published data and our applications |
Regulator figures are quoted as published and converted to months. Our realistic timeline assumes a complete, well-prepared application.
| Item | Amount | Notes |
|---|---|---|
| Application fee | €10,000 | One category of activity |
| Annual supervisory fee | €25,000 fixed plus variable | The higher of 0.02% of total assets or 0.0003% of payment transactions, capped at €250,000; paid in January and July |
| Initial capital | €20,000 to €125,000 | By the highest service |
| Professional fees | Fixed | Quoted after scoping |
A Maltese payment institution passports throughout the EU and EEA under the European passport rights regulations. A limited-network exclusion with annual notification applies above €1 million of transactions.
The MFSA publishes stage-level service targets rather than a list of causes of delay. In our experience the three causes are the same as in every EU regime: incomplete submissions, insufficient substance in Malta, and business plans whose assumptions and flows of funds are not clear.
A payment institution needs a safeguarding account, an operating account and settlement accounts in the currencies it serves. We open each alongside the application, so you trade from authorisation. See banking and payment processing.
Three months from receipt by statute; we plan for six to eight months after submission, including the in-principle approval and conditions stages.
€125,000 for account, card and most services; €20,000 for money remittance only; €50,000 for payment initiation only.
€10,000 on application and a fixed annual fee of €25,000 plus a variable element capped at €250,000.
No. Every payment institution holds the full licence.
Two individuals effectively directing the business, a Malta-resident board member, the key function holders and the control functions.
A regulatory advisory firm to payment, e-money and cryptoasset companies since 2013, with more than 250 licences obtained in more than 60 countries. The firm builds licensed payment, e-money, crypto and stablecoin businesses: the licence, the team, the technology, the bank accounts and card issuing.
This guide is general information, not legal advice. Requirements and fees change, and the regulator’s own publications take precedence.
The licence, your team, banking and technology, delivered as one programme.