 Payment Institution
Obtained Nexpay’s FCA Authorised Payment Institution licence.
WhatsApp and Telegram +44 7563 115980
[email protected]
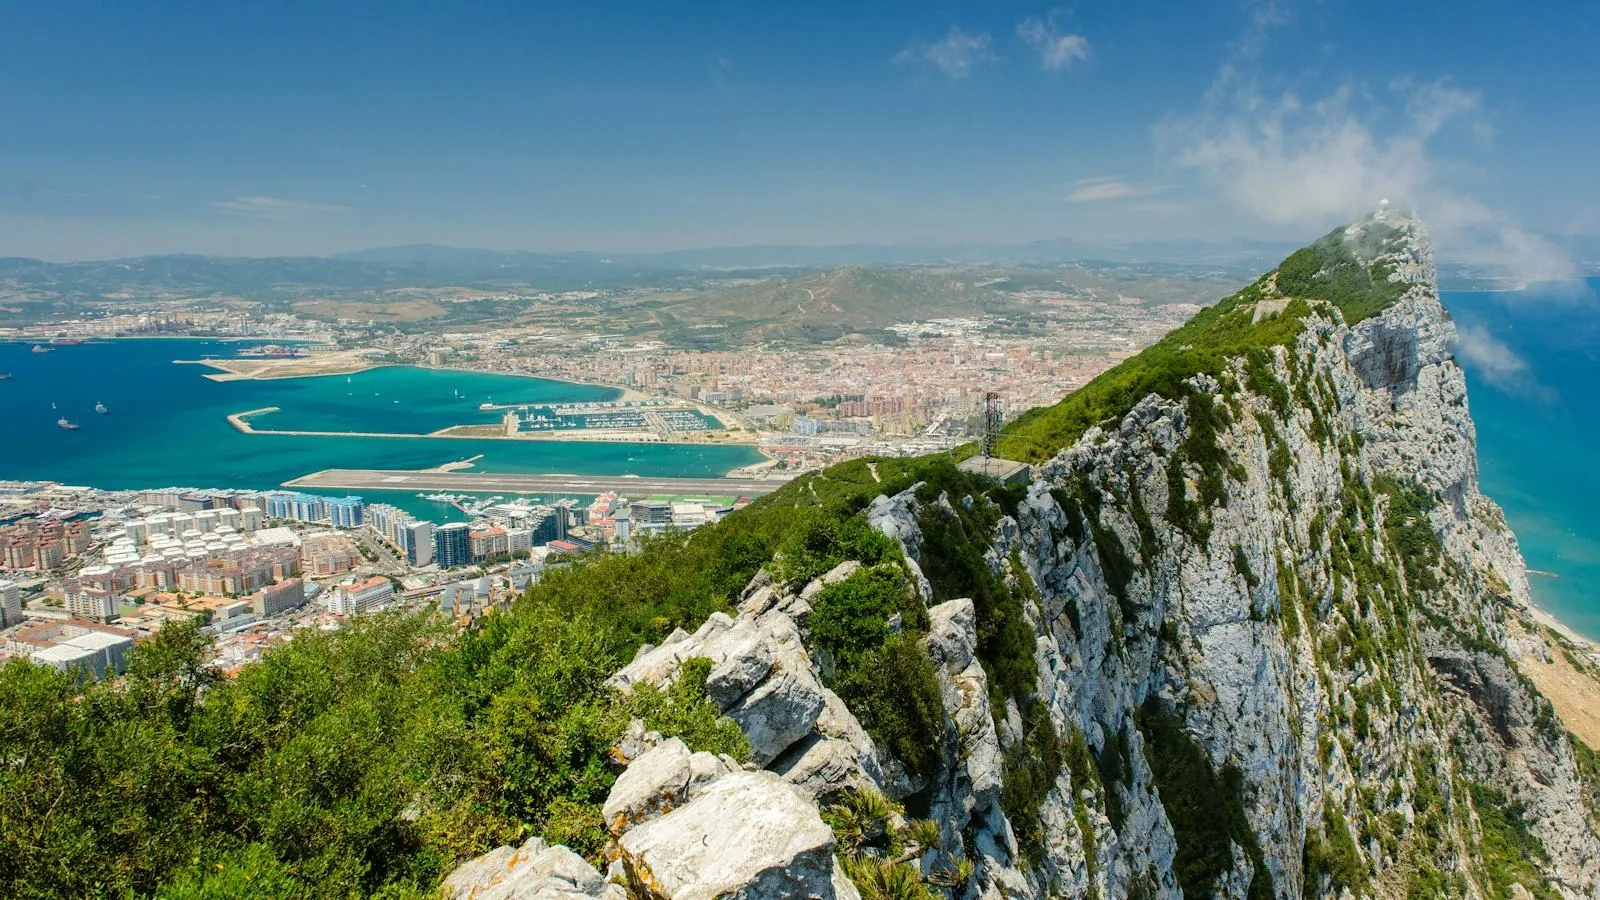
Firms whose main market is the United Kingdom choose Gibraltar for its English law, English-language regulation, published service standards and UK access by passport under transitional arrangements that run to 31 December 2026 and may be extended until the Gibraltar Authorisation Regime takes effect.
Selected engagements from more than 250 licences obtained since 2013, for payment, e-money and cryptoasset firms.
 Volkswagen
 Payment Institution
Obtained Nexpay’s FCA Authorised Payment Institution licence.
 Electronic Money Institution
Obtained Dzing Finance’s FCA Authorised Electronic Money Institution licence.
Obtained Orbital’s FCA Authorised Payment Institution licence.
Our realistic timeline from submission to decision.
Safeguarding, operating and settlement accounts opened alongside the application, so you trade on authorisation.
We assemble your team: senior managers and non-executive directors.
The licence, the requirements, the cost and the timing for your business.
You will need senior managers and non-executive directors, each approved by the GFSC as fit and proper, which takes 30 working days where it holds an interview.
One programme, from scoping to launch. Speak to an expert about this licence.
Requirements, capital, timing, fees and common questions, drawn from the regulator’s own publications.
Any firm issuing e-money, the E-Money Issuer permission, or providing payment services, the Payment Service Provider permission, in or from Gibraltar needs authorisation under Part 7 of the Financial Services Act 2019 and the payment services and e-money regulations made under it. Credit institutions and e-money issuers do not need a separate payment institution licence but obtain permission to carry on payment services; agents of a payment service provider are registered with the GFSC. Gibraltar is chosen by firms whose market is the United Kingdom: a Gibraltar authorisation gives access to the UK under the transitional arrangements and, in due course, the Gibraltar Authorisation Regime, from a jurisdiction with English law, English-language regulation and published service standards.
| Permission | Scope | Initial capital | Passporting |
|---|---|---|---|
| Authorised e-money issuer | Issuing e-money and providing payment services | Higher of €350,000 and 2.2% of average outstanding e-money | UK under transitional arrangements |
| Small (registered) e-money issuer | Issuing e-money within the small regime | 2.2% of average outstanding e-money | None |
| Payment institution, Class A | Money remittance | €20,000 | UK under transitional arrangements |
| Payment institution, Class B | Payment initiation and account information | €50,000 | UK under transitional arrangements |
| Payment institution, Class C | Cash placement and withdrawal, payment execution including direct debits, cards and credit transfers, credit-backed execution, issuing and acquiring | €125,000 | UK under transitional arrangements |
| Registered (small) payment institution | Payment services within the small regime | Not published | None |
| Requirement | Amount |
|---|---|
| Authorised e-money issuer | Higher of €350,000 and 2.2% of average outstanding e-money, projected at application |
| Small (registered) e-money issuer | 2.2% of average outstanding e-money |
| Payment institution, Class A (money remittance) | €20,000 |
| Payment institution, Class B (payment initiation and account information) | €50,000 |
| Payment institution, Class C (execution, issuing and acquiring) | €125,000 |
| Ongoing own funds | Method under the Payment Services Regulations agreed with the GFSC before final approval |
A firm holding several permissions may need the aggregate of the amounts.
| Figure | Value | Source |
|---|---|---|
| Statutory decision period | Up to 12 months to determine an incomplete application plus 3 months for e-money and payment services, 15 months in total | GFSC Service Level Standards under the Financial Services Act 2019 |
| Regulator’s published figure | 9 months maximum for e-money across three stages (5, 2 and 2 months) and 6 months for payment services (3, 2 and 1); the clock starts once the fee is paid and the application is complete and pauses while information is awaited | GFSC Service Level Standards |
| Application preparation | 6 to 8 weeks | From instruction to submission, including banking in parallel |
| Our realistic timeline | 6 to 9 months after submission | Our own figure, from the regulator’s published data and our applications |
Regulator figures are quoted as published and converted to months. Our realistic timeline assumes a complete, well-prepared application.
| Item | Amount | Notes |
|---|---|---|
| EMI application fee | £45,000 | Fee Block A1; paid in full with the Stage 1 submission |
| EMI annual fee | £26,262 base plus e-money fee | E-money fee of £0 to £45,959 by average outstanding e-money, plus £262 per agent and £133 per distributor, plus the passporting fee |
| Payment institution application fee | £11,250 Class A; £22,500 Class B; £45,000 Class C | Fee Block B1; registered payment institution £4,331 |
| Payment institution annual fee | £9,192 base plus additional fees | Additional Fee 1 by class: £9,192 Class A, £13,167 Class B, £17,070 Class C, £6,568 registered; a turnover-based Additional Fee 2; £262 per agent; the passporting fee |
| Agent appointment | £250 | Per agent |
| Passporting annual fee | £1,030 services; £5,150 establishment | Payable with the annual fee |
| UK passport application | £3,000 services; £3,500, £11,000 or £40,000 establishment | Establishment fee by complexity: non-complex, moderately complex, complex; agent passport notification £3,000; the FCA charges no notification fee |
| Professional fees | Fixed | Quoted after scoping |
A small, registered e-money issuer holds capital of 2.2% of average outstanding e-money and may not passport; a registered payment institution applies for £4,331 and pays a reduced annual fee. The GFSC’s pages state no thresholds for either regime.
| Stage | Content | E-money | Payment services |
|---|---|---|---|
| Pre-application | Introductory meeting, abridged business plan, follow-up meeting with written feedback | Within 4 weeks | Within 4 weeks |
| Stage 1 | Business model, capital, key individuals: application form, Stage 1 of the comprehensive business plan, controller forms, transfer pricing evidence; fee paid in full; supervisor assigned | 5 months | 3 months |
| Stage 2 | Risk, IT and cyber, governance, business continuity, outsourcing, financial crime and AML/CFT, risk framework and register, disaster recovery | 2 months | 2 months |
| Stage 3 | Conduct, compliance structure, remuneration, conflicts, liquidity and solvency, internal audit, complaints, Consumer Duty and operational resilience where applicable; signed Regulated Individual and non-executive director forms; professional indemnity insurance; mobilisation plan | 2 months | 1 month |
| Total service standard | Clock starts after the fee is paid and a complete application is received; pauses while information is awaited | 9 months | 6 months |
Regulated Individual approvals take 30 working days with an interview and 10 without. The GFSC gives monthly progress updates and publishes quarterly authorisation statistics: in the second quarter of 2026 the e-money sector recorded 3 Regulated Individual applications, all approved within the 30-day standard, and in the first quarter 2 applications, both approved within 30 days.
EU passporting ended with Brexit. A Gibraltar-authorised firm may carry on its permitted activities in the United Kingdom by branch or cross-border services under Gibraltar’s Financial Services (Passport Rights and Transitional Provisions) (EU Exit) Regulations 2020 and the UK’s Financial Services (Gibraltar) (Amendment) (EU Exit) Regulations 2019, which have effect until 31 December 2026 and may be extended until the Gibraltar Authorisation Regime comes into effect; the FCA confirms the arrangement runs until 31 December 2026 and may be extended, and the deadline was extended on 11 December 2023, 10 January 2025 and 19 December 2025. The regime itself is in section 22 and Schedule 6 of the Financial Services Act 2021, inserting Schedule 2A into FSMA 2000; the insertion came into force on 1 September 2023 for specified purposes only and full commencement is phased, so at October 2026 the transitional arrangements continue. A UK passport is a material change needing section 83A consent, then a notification to the GFSC, which notifies the FCA; the FCA processes it within one month under regulation 27(3) of the Payment Services Regulations 2017 and charges no fee. Passporting services is classed non-complex; passporting a branch is complex. Registered e-money issuers may not passport.
The GFSC publishes how its standards operate. The service-level clock starts only once the fee is paid and the application is complete, and pauses while the GFSC awaits requested information; progression between stages depends on the GFSC being satisfied with each stage; a rejection or conditions add one month to variation and change of control timelines; and pre-application feedback is not an indicator of the final decision. The points settled before Stage 1 are the class, the capital and its source, the controllers and Regulated Individuals, and the safeguarding arrangement.
An EMI needs a safeguarding account that satisfies the GFSC’s requirements, an operating account and settlement accounts in the currencies it serves; a payment institution needs the same without the e-money float. We open each alongside the application, so you trade on authorisation. See banking and payment processing.
The statutory maximum is 15 months. The GFSC’s service standard is 9 months for e-money across three stages and 6 months for payment services, with the clock paused while it awaits information. We plan for six to nine months after submission.
£45,000 on application for an EMI and £11,250, £22,500 or £45,000 for a payment institution by class, with annual base fees of £26,262 and £9,192 plus additional fees by e-money outstanding, class, turnover and agents.
Yes, by branch or cross-border services under transitional arrangements in effect until 31 December 2026, which may be extended until the Gibraltar Authorisation Regime takes effect. The passport is a material change needing GFSC consent and a notification to the FCA.
No. EU passporting ended with Brexit; groups serving the EU hold an EU authorisation alongside, which we obtain.
Yes: a registered e-money issuer at 2.2% of average outstanding e-money and a registered payment institution with a £4,331 application fee, neither of which may passport; the GFSC’s pages state no thresholds for either.
A regulatory advisory firm to payment, e-money and cryptoasset companies since 2013, with more than 250 licences obtained in more than 60 countries. The firm builds licensed payment, e-money, crypto and stablecoin businesses: the licence, the team, the technology, the bank accounts and card issuing.
This guide is general information, not legal advice. Requirements and fees change, and the regulator’s own publications take precedence.
The licence, your team, banking and technology, delivered as one programme.