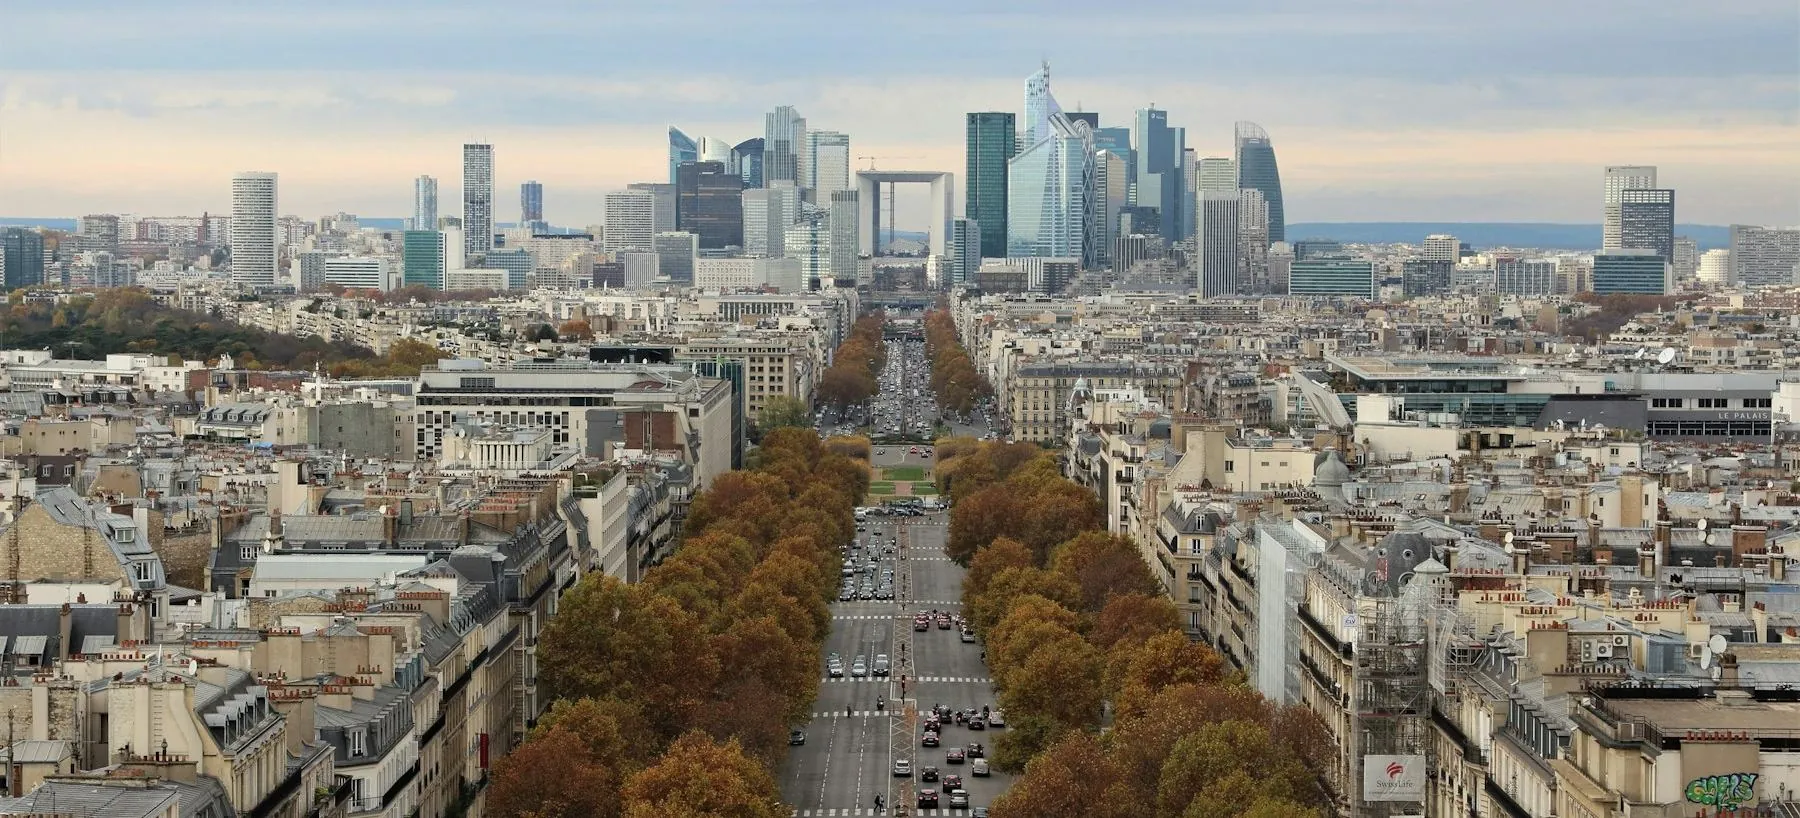
La Défense from the Arc de Triomphe
Home › Licensing › France › France EMI licence
Licence guide

France electronic money institution licence.

France gives e-money issuers the EU’s second-largest payments market and a regulator that commits to response times at each stage, with a simplified route for smaller issuers.

Published 16 October 2026 · Last reviewed 17 October 2026
ACPRRegulator
€350,000Initial capital
NoneApplication fee
6 to 8 monthsOur realistic timeline
EU and EEAPassporting

Firms we have licensed.

Selected engagements from more than 250 licences obtained since 2013, for payment, e-money and cryptoasset firms.
Since 2013Advising global payment firms
60+Countries licensed in
250+Licences obtained globally
Clients
ClearBankVolkswagenMacmillan Cancer SupportRoyal College of MusicStaysureOval MoneyEMQCentus
nexpayPayment Institution

Obtained Nexpay’s FCA Authorised Payment Institution licence.
dzingElectronic Money Institution

Obtained Dzing Finance’s FCA Authorised Electronic Money Institution licence.

Payment Institution

Obtained Orbital’s FCA Authorised Payment Institution licence.

What you get

6 to 8 monthsLicence granted

Our realistic timeline from submission to decision.

Day oneReady to trade

Safeguarding, operating and settlement accounts opened alongside the application, so you trade on authorisation.

Your teamKey people in place

We assemble your team: two managing directors based in France.

Same dayWritten proposal

The licence, the requirements, the cost and the timing for your business.

How we get you licensed and live

  1. Scoping and proposal. We confirm the route, full or simplified, and the own funds in a written proposal, and request the mandatory project presentation meeting with the ACPR’s authorisations directorate, which the ACPR holds within two weeks.
  2. Application pack. The file in the format of the ACPR’s instruction: business plan, three-year projections with target and stressed scenarios and their formulas, the draft safeguarding agreement, internal control and the manager files, filed on the ACPR portal.
  3. Banking. The dedicated safeguarding account (cantonnement) and the operating accounts, opened alongside the application, on account terms and transfer timing that meet the ACPR’s safeguarding expectations.
  4. Regulator engagement. We answer the ACPR’s clarification requests, issued within three weeks of filing, and support the Banque de France’s payment security opinion, through to the decision of the ACPR’s college and the lifting of conditions precedent.

Your team, banking and technology

You will need at least two managing directors running the business from France, with the key control roles held by your own staff rather than outsourced.

Key peopleWe assemble your team: two managing directors based in France.
BankingSafeguarding, operating and settlement accounts, card acquiring and payment processing, opened alongside the application.
TechnologyWhite-label technology for accounts, payments, wallets and card programmes, ready to go live with the licence.

One programme, from scoping to launch. Speak to an expert about this licence.

The licence in detail

Requirements, capital, timing, fees and common questions, drawn from the regulator’s own publications.

Key takeaways
  • A French EMI issues e-money and provides payment services across the EU and EEA on one authorisation from the ACPR, backed by the Banque de France.
  • Initial capital is €350,000; own funds are 2% of average outstanding e-money.
  • There is no application fee; an annual supervision contribution applies.
  • Three months from a complete file by statute; the ACPR commits to stage-level response times under its Fintech Charter.
  • Effective management by at least two persons in France, with the central administration in France.
  • A simplified authorisation with €100,000 capital exists below €5 million of average monthly outstanding e-money, without passporting.

Who needs the licence

A business issuing stored value in France or, through passporting, across the EU and EEA needs ACPR authorisation. France is the EU’s second-largest payments market and the ACPR publishes its procedure, its points of attention and stage-level service commitments. An EMI may provide every payment service under the same authorisation.

What the ACPR requires

  • Legal form and location. A company whose central administration is in the same territory as its registered office, with effective management exercised in France by at least two persons and key functions held internally; responsibility stays in France whatever is outsourced.
  • Governance. At least two effective managers meeting the tests of honourability, knowledge, experience and competence; a documented allocation of responsibilities; risk management, internal control and an AML framework; an opinion from the Banque de France on payment security before authorisation.
  • Safeguarding. Segregation on a dedicated demand account, or an insurance contract or comparable guarantee; funds remaining at the end of the next business day moved to the dedicated account; daily safeguarding, including weekends, where instant transfers are offered; the draft safeguarding agreement in the file.
  • Application pack. A mandatory project presentation meeting with the ACPR’s authorisations directorate, then the file on the ACPR portal in the format of the ACPR’s instruction: business plan, three-year projections with target and stressed scenarios, programme of operations, governance, internal control, AML, IT and security, and the manager files.
  • Capital. Initial capital of €350,000 and own funds thereafter of 2% of average outstanding e-money; €100,000 under the simplified regime.

Capital

RequirementAmount
Initial capital€350,000
Ongoing own funds (Method D)2% of average outstanding e-money
Simplified authorisation€100,000; average monthly outstanding e-money not above €5 million

Institutions below €5 million of outstanding e-money file a reduced set of prudential returns.

Timing

FigureValueSource
Statutory decision period3 months from a complete file; silence is refusalMonetary and Financial Code
Regulator’s published figurePresentation meeting within 2 weeks; clarification requests within 3 weeks of filing; replies within 2 weeks; decision posted within 2 business daysACPR Fintech Charter
Application preparation6 to 8 weeksFrom instruction to submission, including banking in parallel
Our realistic timeline6 to 8 months after submissionOur own figure, from the regulator’s published data and our applications

Regulator figures are quoted as published and converted to months. Our realistic timeline assumes a complete, well-prepared application.

Fees and costs

ItemAmountNotes
Application feeNonePassport notifications are also free
Annual supervision contributionSet under the monetary and financial codeAmount by institution type
Initial capital€350,000€100,000 under the simplified regime
Professional feesFixedQuoted after scoping

Simplified authorisation

An issuer whose average monthly outstanding e-money stays below €5 million, with units limited to €250, may apply for the simplified authorisation: €100,000 capital and adapted own funds and internal control, with no European passport.

Passporting and scope

A French EMI passports throughout the EU and EEA by branch, agent or distributor, or cross-border services, on notification through the ACPR portal after authorisation. The simplified regime carries no passport.

Why applications are delayed

The ACPR publishes its points of attention.

  1. Incomplete or unfinished files and slow responses to questions.
  2. Safeguarding arrangements that do not comply: account terms, timing of transfers, the terms of the dedicated account.
  3. Own funds and business plan weaknesses: ineligible capital instruments, missing three-year profit and loss, balance sheet and cash flow with target and stressed scenarios, spreadsheets without their formulas.

Your bank accounts

An EMI needs a safeguarding account, an operating account and settlement accounts in the currencies it serves. We open each alongside the application, so you trade from authorisation. See banking and payment processing.

Common questions

How long does ACPR EMI authorisation take?

Three months from a complete file by statute, with silence treated as refusal. The ACPR commits to a presentation meeting within two weeks, clarification requests within three weeks of filing and replies within two weeks. We plan for six to eight months after submission.

Is there an application fee in France?

No. Passport notifications are also free. An annual supervision contribution applies once authorised.

What is cantonnement?

Segregation of customer funds on a dedicated demand account with a credit institution, the French safeguarding method; an insurance contract or comparable guarantee is the alternative.

Who must be in France?

At least two effective managers exercising management from France, with the central administration in the same territory as the registered office.

What is the simplified EMI regime?

An authorisation for issuers below €5 million of average monthly outstanding e-money with €100,000 capital and no passport.

References

  1. ACPR: payment institution authorisation procedure
  2. ACPR: electronic money institution authorisation procedure
  3. ACPR: points of attention in the examination of authorisation files
  4. ACPR Fintech Charter
  5. ACPR and AMF Fintech Forum 2025, payments workshop

About Buckingham Capital Consulting

A regulatory advisory firm to payment, e-money and cryptoasset companies since 2013, with more than 250 licences obtained in more than 60 countries. The firm builds licensed payment, e-money, crypto and stablecoin businesses: the licence, the team, the technology, the bank accounts and card issuing.

This guide is general information, not legal advice. Requirements and fees change, and the regulator’s own publications take precedence.

How we work.

  • Senior-ledThe same senior team handles your application from the first call to approval, including every question the regulator raises.
  • Same dayA reply within three business hours and a written proposal the same day: the licence, the requirements, the cost and the timing.
  • ConfidentialYour plans, your application and any listing stay private. Clients are named only with their agreement.
  • Live workspaceDocuments, regulator questions, messages and progress in a shared client workspace, visible to your team at every stage.

Why firms choose BCC.

  • OperatorsWe have run regulated payment businesses, held regulator-approved roles and licensed payment firms in more than 60 countries since 2013.
  • One teamOne in-house team runs the whole programme, from the application to the day you go live.
  • ArrangedBank and safeguarding accounts, card issuing and payment processing, arranged directly through our relationships with banks, card schemes, issuers and processors.

Apply for this licence.

The licence, your team, banking and technology, delivered as one programme.